---
title: KONNECT - OCTOBER 2026
description: Discover the latest insights on the maritime industry challenges, global shipping trends, and economic impacts in Oceania - October 2026 update.
image: https://info.oceania.kln.com/hubfs/banner%20konnect%202026%202.png
---
[](https://oceania.kln.com)
- About us
- [Our Team](https://oceania.kln.com/about-us/team)
- [Oceania at a glance](https://oceania.kln.com/about-us/oceania-at-a-glance)
- [Sustainability](https://oceania.kln.com/about-us/sustainability)
- [Global network](https://oceania.kln.com/about-us/global-network)
- Content
- [KnowledgeHub](https://info.oceania.kln.com/knowledgehub)
- [Konnect](https://info.oceania.kln.com/konnect)
- [Customer Advisories](https://info.oceania.kln.com/customer-advisory)
- [Downloads & Resources](https://info.oceania.kln.com/downloads-resources1)
- Solutions
- [VBO - Supply Chain Command Center](https://info.oceania.kln.com/vbo)
- [KLN Online](https://info.oceania.kln.com/kln-online-solutions)
- Freight
- [Ocean Freight](https://info.oceania.kln.com/ocean-freight)
- [Air Freight](https://info.oceania.kln.com/air-freight)
- [Land Freight](https://oceania.kln.com/solutions/land-freight)
- [Multimodal](https://oceania.kln.com/solutions/multimodal)
- [Customs Brokerage](https://oceania.kln.com/solutions/customs-brokerage)
- [Cargo Insurance](https://info.oceania.kln.com/cargo-insurance)
- [Supply Chain Solutions](https://oceania.kln.com/solutions/supply-chain-solutions)
- [Consolidation](https://oceania.kln.com/solutions/consolidation)
- [Integrated Logistics](https://oceania.kln.com/solutions/integrated-logistics)
- Locations
- [Australia](https://oceania.kln.com/locations/australia)
- [Aotearoa New Zealand](https://oceania.kln.com/locations/aotearoa-new-zealand)
- [Global network](https://www.kln.com/en/network/)
- [Track & Trace](https://oceania.kln.com/track-trace)
- [Contact](https://info.oceania.kln.com/contact)
- [Subscribe](https://info.oceania.kln.com/subscribe-communications)
- [Home](https://kerrylogisticsoceania.com/)
- [Articles](https://info.oceania.kln.com/konnect)
- [Konnect](https://info.oceania.kln.com/konnect/tag/konnect)
# KONNECT - OCTOBER 2026
02 Oct 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [2026](https://info.oceania.kln.com/konnect/tag/2026)
- [](http://www.facebook.com/sharer/sharer.php?u=https://info.oceania.kln.com/konnect/konnect-october-2026)
- [](https://twitter.com/intent/tweet?url=https://info.oceania.kln.com/konnect/konnect-october-2026&text=KONNECT%20-%20OCTOBER%202026)
- [](http://www.linkedin.com/shareArticle?mini=true&url=https://info.oceania.kln.com/konnect/konnect-october-2026)
- [](mailto:?body=https://info.oceania.kln.com/konnect/konnect-october-2026)
- Copy to clipboardLink Copied
https://info.oceania.kln.com/konnect/konnect-october-2026

### 
☰ On this page
On this page
×
↑ Back to top
‹
## Executive Summary
September arrived as the month all of 2026's compounding pressures converged simultaneously. The Strait of Hormuz recorded its lowest commercial throughput since the crisis began, with just one vessel transiting on 27 September against a pre-crisis baseline of approximately 85 per day. The RBA delivered a fourth rate hike of the year, lifting the cash rate to 4.60% — its highest level since November 2011. China's east coast, already congested from a succession of typhoons through August, absorbed the Golden Week freight surge hitting a system with almost no slack remaining. And carriers moved to lock in October rate restorations on Asia-Oceania lanes before the final Christmas cargo window closes. For importers and exporters across Australia and New Zealand, Q4 has opened under a heavier cost and schedule burden than any equivalent period in recent years.
Seven months in, the Strait of Hormuz is at its most closed. September's diplomatic activity was, paradoxically, the most substantive of the year: Iran and Oman agreed precise coordinates for a middle corridor through the strait, resolving what had been the central technical sticking point for weeks. Iran's Foreign Minister then presented a seven-day reopening plan at the United Nations on 25 September, conditional on the US halting hostilities, lifting its naval blockade, and releasing frozen assets. The US issued a counterproposal. As of 30 September, Iran is reviewing it. This is the closest the two sides have come to a structured reopening framework — but no transit has resumed on the strength of it, war-risk premiums reached 40 times pre-crisis levels during the month, and vessel attacks continued, including an Iranian strike on the Kuwaiti supertanker Al Funtas on 28 September and the death of a seafarer aboard the bulk carrier Cape Dao on 23 September. The total vessel attack count since February now exceeds 100. Cape of Good Hope routing remains the only commercially viable standard for major carriers, and that will not change until a sustained, insurable reopening is confirmed.
The US tariff landscape has settled into a new baseline — for now. The 12.5% Section 301 forced-labour tariff on Australian and New Zealand goods, in force since 24 July, holds with no expiry date and no confirmed review timeline. Key exemptions remain in place for Australian beef and gold, and New Zealand beef and kiwifruit, but the rate is a standing cost for all other affected product lines and should be treated accordingly. The separate Section 232 proposal to extend metals tariffs to 14 derivative steel, aluminium, and copper products closed its public comment period on 27 August without a published outcome — a status that remains unresolved entering October. Exporters with metal-containing products shipping to the US should keep HS classifications under active review, as the Commerce Department can publish findings with limited notice. On the positive side, the New Zealand-India Free Trade Agreement enters into force on 20 October, with 57% of New Zealand exports to India entering duty-free from day one and a clear implementation path to 82% at full implementation.
Domestically, both central banks have now committed clearly to their respective directions. The RBA's 29 September decision was unanimous — a departure from the divided votes of earlier in the year — and the Board's statement left the door open to a fifth hike in November, with the September quarterly CPI due 28 October as the pivotal input. ANZ is forecasting a further move to 4.85%; CBA and Westpac have shifted to a hold position. In New Zealand, the RBNZ's September Monetary Policy Statement confirmed the OCR is heading to 3.0% by December, with a pause expected at the 28 October meeting and a final 25 basis point move in December. New Zealand's August trade deficit widened to NZD 1.3 billion for the month and NZD 5.4 billion annually — the fuel import cost surge is now clearly visible in the trade balance data. For Oceania supply chains entering Q4, October rate restorations are landing on Asia-Oceania lanes, Brisbane and Melbourne port congestion remains significant, pre-Christmas cargo cut-offs in New Zealand are as early as 30 October for feeder ports, and DAFF's second phase of biosecurity cost recovery changes takes effect 1 November. The window to act on Q4 freight planning is this month, not next.
## Business Tip
**Treat October bookings as your Christmas deadline — and cost them at today's exchange rate, not last quarter's.**
With restorations from 15 October, a likely peak season surcharge from mid-October and space tightening into November, the cheapest and most reliable option for most peak cargo is to book now, at least three to four weeks ahead of cargo-ready date. Confirm actual transit estimates for your lane rather than relying on proforma schedules, particularly for Brisbane and Melbourne. Re-run your landed-cost model with an AUD near 70 US cents (or NZD near 57 US cents) and current fuel surcharges, so pricing and margin decisions reflect conditions as they are. Speak to your KLN Oceania account manager to review your Q4 booking plan and confirm space before the 15 October increases take effect.
### [](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)
## Spotlight
Asia to Oceania, on the Aircraft That Actually Has Space
When cargo can't wait for a vessel, speed is a given. The real question is whether your forwarder can find capacity on the day you need it, at a price that still makes commercial sense.
This peak season, that question matters more than usual. Shanghai to Brisbane is running at 31 days on a typical sailing and up to 47 days in a worst case. Carriers are omitting port calls, and rates rise again from 15 October. Air freight moves the same Asia–Oceania cargo in around three to five days, against roughly 30 days by ocean.
KLN Oceania connects Australia and New Zealand to Asia's major manufacturing markets through KLN's air network across the region. It is backed by a local team that knows your lanes and answers the phone
[](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLI7kskzaKxB1%2F8HS3cK9D2NsVCQSndkm3ucE9RQ5bnt%2BVx9bPMu%2BWExS%2FTbfAb%2B56M3MzXn%2BZFHwnrD6g%2BWqF9FCYKjO3xQ3sGe5HM2qBYdM5dvePLG%2FB7t8C7GQOj9ZnkE5DoDE%2BOsSfZUj5Ss0TYwrIKTE8ZxNKX%2BNGGe04xvAuv%2FFZn5eO8Xi671QlQT00o3mrITvdSPyLB0Q37Wfrer&webInteractiveContentId=132374676891&portalId=40234550)
## Market Trend
September was the month the full weight of 2026's compounding pressures arrived at once. The Strait of Hormuz deteriorated to its lowest commercial throughput since the crisis began, with just one vessel transiting on 27 September against a baseline of 85 per day. The RBA delivered its fourth rate increase of the year, taking the cash rate to its highest level since 2011. And China's east coast — already congested from a succession of typhoons through August — faced the Golden Week freight surge hitting an already-stressed system, with the usual pre-holiday compression squeezed into just three working days.
### **Middle East: Crisis Month 7 — The Strait at Its Most Closed Since February**
September produced the most complete closure of the Strait of Hormuz since the crisis began on 28 February 2026. PortWatch recorded just one commercial transit on 27 September, against a pre-crisis baseline of approximately 85 per day. War-risk insurance premiums reached 40 times their pre-crisis levels, and the Hormuz Live Tracker's crisis pressure index reached its highest reading. Oil prices rose sharply in early September — Brent settled at USD 96.28 on 4 September, up 7.6% in a single week — the highest level of the conflict. As of 30 September, Iran is reviewing a US ceasefire counterproposal, with Hormuz terms still unresolved.
The month's diplomatic activity produced the most detailed framework for reopening yet seen, without actually reopening the strait. By 15 September, Iran and Oman had agreed coordinates for a 'middle corridor' through the strait — a compromise route between Iran's preferred northern passage through Iranian waters and the US-backed southern route along Oman's coast. This was a significant technical breakthrough: the precise corridor coordinates had been the central sticking point for weeks. Iran's IRGC confirmed the agreement. But on 25 September, Iran's Foreign Minister Abbas Araghchi presented a seven-day plan at the United Nations: if the US halts fighting, lifts its naval blockade, releases frozen assets, and suspends oil sanctions, Iran would allow the strait to reopen at the end of day seven. The US issued a counterproposal. As of 30 September, Iran is reviewing it.
The month also produced further violence. On 23 September, a seafarer aboard the bulk carrier Cape Dao was killed by an Iranian strike off Oman — bringing the confirmed death toll among seafarers and port workers to at least 21 since the conflict began. On 28 September, the IRGC struck the Kuwaiti supertanker Al Funtas in the strait. The total number of vessel attacks recorded since February now exceeds 100, according to UKMTO data. At least 6,000 sailors remain stranded aboard hundreds of vessels in the Persian Gulf.
**What this means entering October**
- Cape of Good Hope routing remains the only commercially viable option for all major carrier services. The middle-corridor agreement between Iran and Oman has not been implemented, and the US counterproposal is under review. Even if talks progress quickly, carriers will not reverse routing decisions until a sustained reopening is confirmed and insurable.
- Oil prices at USD 96 per barrel (Brent, early September peak) represent elevated bunker cost conditions that are keeping Emergency Fuel Surcharges active across carrier networks. Confirm current FSC schedules before finalising freight costs.
- The closest thing to genuinely positive news in September was the middle-corridor coordinates agreement. This is the first time both sides have agreed on the physical pathway for a potential reopening. Monitor diplomatic developments in early October closely — progress from the US counterproposal review could shift the market picture quickly.
**Tariff Watch: Section 301 Holds, Section 232 Still Pending**
The US Section 301 "forced labour" tariff of 12.5% on Australian and New Zealand goods, in force since 24 July 2026, remains unchanged, with no review or expiry date. It applies on top of normal duty, but does not stack on goods already subject to Section 232 metals tariffs. Key exemptions remain in place, including beef and gold for Australia, and beef and kiwifruit for New Zealand.
The proposed extension of Section 232 duties to 14 further steel, aluminium and copper derivative products, mostly at 25%, had not been finalised as of 23 September, almost four weeks after public comment closed on 27 August. Separately, the US expanded Section 232 tariffs to patented pharmaceuticals (100%) from 29 September.
**What this means for Oceania businesses**
Exporters to the US should continue to price in the 12.5% duty as a standing cost, not a temporary measure. Businesses shipping metal-containing products should keep HS classifications under review, as the Section 232 derivatives decision could be published with little notice.
### [](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)
### **Developments in Oceania**
#### Australia's Economic Outlook
The RBA delivered a fourth rate hike for 2026 at its 29 September meeting, lifting the cash rate by 25 basis points to **4.60%** — the highest level since November 2011 and the peak that the major banks had been forecasting since mid-year. The decision was unanimous, a clean signal from the Board that its members had coalesced around the case for further tightening after two consecutive holds in June and August. In its accompanying statement, the Board noted that some of the upside risks it had flagged in August have now materialised, cited higher fuel prices from the Middle East conflict as feeding broader inflationary pressure, and left the door open to further increases "if needed." The statement language around cumulative tightening and economic slowing was retained, but the active tightening bias remained intact.
The August CPI, released by the ABS on 30 September — the day after the rate decision — confirmed why the Board moved. Annual headline inflation rebounded to **4.0%**, up from 3.5% in July and fractionally below the 4.1% consensus forecast. The monthly rise of 0.4% in original terms and 0.7% seasonally adjusted underscores that price pressures are not yet on a sustained downward path. Housing was the largest contributor at 5.7% annually, with new dwelling prices rising 5.4% as builders continue passing on elevated material and labour costs and electricity costs rising again as government rebates remain fully expired. Transport was the second largest contributor at 5.6% annually, driven by automotive fuel — a dynamic directly linked to the Middle East conflict and the partial unwinding of the federal excise relief measures in July. The trimmed mean held at **3.6%** for the third consecutive month, with both automotive fuel and electricity excluded from the calculation. The Board went into September's meeting without this August read; its arrival the following morning will inform November's discussion.
ANZ is now the most hawkish of the major banks, forecasting a fifth hike in November to 4.85%. CBA and Westpac have shifted to a hold position for November, citing cumulative tightening and an economy that appears to be slowing as intended. Markets briefly priced the cash rate above 5% by mid-2027 before retreating after Governor Bullock declined to ratify that trajectory at her post-decision press conference, signalling that the Board remains data-dependent rather than committed to a fixed path. The next meeting is scheduled for 3 November 2026, with the September quarterly CPI — due 28 October — as the pivotal data point ahead of it.
#### New Zealand's Economic Developments
The most significant New Zealand monetary policy development in September is the formal confirmation of the RBNZ's tightening path following its 2 September Monetary Policy Statement, which lifted the OCR to **2.75%** by consensus. The June 2026 quarter CPI, released in late July, came in at **4.1%** — above the RBNZ's May forecast of a 3.9% peak — a result that shaped the September MPS and prompted the Bank to revise its domestic inflation forecasts for 2027 upward, reflecting expectations of persistent domestic price pressures rather than a clean and rapid return to target. A majority of MPC members assessed inflation risks as skewed to the upside; all members saw downside risks to growth.
The RBNZ's current path projects a pause at the 28 October meeting — the next scheduled decision — and a further 25 basis point hike in December to 3.0%, broadly consistent with what the Bank has signalled as the neutral rate level. Westpac's post-MPS review describes the stance as "appropriately balanced" and sees the Bank wanting to observe the durability of the recovery before committing to hikes beyond December. Services NZ quarterly overseas trade index data, released 3 September, showed import prices rising **13.7% quarter-on-quarter and 15.2% year-on-year** in the June 2026 quarter — a stark illustration of the fuel shock's pass-through into the import cost base.
August trade data, released by Statistics New Zealand on 18 September, showed a monthly goods trade deficit of **NZD 1.3 billion**, with goods exports rising 15% year-on-year to NZD 6.7 billion and imports rising 13% to NZD 8.0 billion. The annual trade deficit widened to NZD 5.4 billion for the year ended August — significantly wider than the NZD 3.2 billion deficit in the same period a year earlier, reflecting the sustained fuel import cost surge. On the export side, partner performance was broadly positive: exports to China rose 23.5%, to the US 42.8%, to Australia 18.4%, and to Japan 6.9%. Import growth was driven by China, South Korea, and the EU. The US import share fell 8.9%, consistent with ongoing trade policy caution around the bilateral relationship.
#### Trade & Industry Highlights
September marked a decisive moment in both economies' policy cycles. Australia's fourth hike of 2026 — 100 basis points in total this year — takes the cash rate to a 15-year high, with the RBA signalling it will act again if inflation does not respond. New Zealand's RBNZ, now two hikes into its own tightening phase, is managing the delicate task of returning above-target inflation to the 2% midpoint while avoiding unnecessary disruption to a recovery that remains uneven and sensitive to external conditions.
The common thread running through both economies remains the Middle East conflict. Its energy cost effects are still feeding visibly through headline CPI in Australia — the 4.0% August read is partly a transport and fuel story — and through New Zealand's import price index, which recorded its steepest annual rise in years in the June quarter. Oil prices have moderated from their conflict-era peaks, which is why both central banks are cautious about the medium-term inflation path rather than alarmed, but second-round effects through construction, food distribution, and transport surcharges are proving stickier than initially expected.
For Oceania importers and exporters entering Q4 2026, the planning environment is defined by: a cash rate at 4.60% in Australia with at least one more hike possible in November, meaning financing and working capital costs remain under active upward pressure; a New Zealand OCR at 2.75% and heading toward 3.0% by December, with domestic inflation still above target and the trade deficit widening on fuel import costs; and an August CPI rebound in Australia that will keep the RBA on alert through the November meeting. The window for settled cost assumptions remains closed. Landed cost modelling, freight contract reviews, and working capital planning should all reflect an environment where rates in both markets are still moving.
[](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)
## Ocean Freight Updates
### **October Rate Restorations and the Christmas Cargo Window**
Carriers are moving to lift Oceania rates ahead of the final peak. ANL has published three rate restorations, all effective 15 October 2026 and applied on top of current spot and FAK rates:
• North East Asia to Australia: USD 500 per 20' / USD 1,000 per 40'
• South East Asia, Indian subcontinent and Middle East to Australia: USD 300 per 20' / USD 600 per 40'
• China, South East Asia, North East Asia, Indian subcontinent and Middle East to New Zealand: USD 600 per 20' / USD 1,200 per 40'
These follow the two USD 500/TEU increases on China/Asia–Australia lanes on 1 and 15 September. KLN Oceania also expects a late-season peak season surcharge window from mid-October to mid-November. This is a forecast rather than a confirmed announcement, and New Zealand-specific restoration and PSS levels are still being confirmed by carriers.
October is the last realistic window for Christmas cargo from Asia. Through November and December, available space — rather than price — is expected to become the main constraint. For New Zealand, pre-Christmas cargo cut-offs have been flagged at 6 November for direct ports and 30 October for feeder ports.
**What this means for Oceania businesses:**
Importers with peak-season stock still to ship should book at least three to four weeks ahead and aim to secure space before 15 October. Cargo shipped after mid-October should be budgeted with both the restoration and a possible PSS included.
### Golden Week and China Port Congestion
China's [Golden Week holiday runs from 1 to 7 October](https://info.oceania.kln.com/knowledgehub/golden-week-2026-shipping-guide-dates-delays-and-booking-deadlines-for-au-nz-importers), following the Mid-Autumn Festival on 25–27 September, leaving only three regular working days between the two holidays. Drewry's cancelled sailings tracker shows 77 blank sailings on the main East–West trades across weeks 39–43, around 11% of scheduled departures.
Congestion at Chinese ports has eased from its August peak but remains significant. For the week of 16–22 September, average vessel waiting times were 4.7 days at Shanghai (six to eight days at Yangshan and Waigaoqiao terminals), 2.5 days at Ningbo and 1.2 days at Qingdao, where berth dredging runs from 15 September to year-end. Yantian continues to apply gate-in restrictions, and 40' high cube equipment is tight at Chinese ports. Globally, Linerlytica estimates 3.76 million TEU of capacity is tied up in congestion, around 10.9% of the fleet.
No major China port closures were recorded from typhoons in September, although Typhoon Dujuan closed Yokohama for 45 hours on 20–22 September
**What this means for Oceania businesses**
Expect a post-Golden Week backlog at origin through mid to late October, with roll-overs possible on popular sailings. Cargo-ready dates in the first half of October should be confirmed with suppliers now, as factory output will pause over the holiday.
### Australian and New Zealand Port Conditions
In Australia, Melbourne has now joined Brisbane as a congestion point. KLN Oceania's current transit estimates are 25 days for Shanghai to Sydney and Melbourne, and 31 days for Shanghai to Brisbane, with a worst case of 41–47 days for Brisbane. Service changes in September included rotation changes and port omissions on several Asia–Australia services, including OOCL and COSCO sailings on the A3S service and ANL omitting Shanghai and Ningbo on 16 September. Maersk has also advised schedule adjustments on its Qilin service.
On the landside, ACFS Port Logistics, Australia's largest port container transport operator, has been in administration since 10 August and continues to trade without disruption to services. At Flinders Ports in South Australia, unions are moving toward protected industrial action. Maersk's revised terminal handling charges in Australia take effect from 1 October.
In New Zealand, alternating port omissions continue on several Asia services, affecting Shanghai, Ningbo, Kaohsiung and Yantian calls. CMA CGM's suspension of Europe–New Zealand bookings via Asia remains in place. On the capacity side, MSC's new Northern Loop (Sydney–Auckland–Napier–Tauranga) began in mid-September and ANL's Tasman Trader resumes its New Zealand rotation from Auckland on 29 October. Port of Tauranga received fast-track approval for its Stella Passage expansion on 7–8 September, which will lift capacity from around 1.2 million to 2 million TEU over time. Manawatu Inland Port will close on 27 November 2026
**What this means for Oceania businesses**
Delivery commitments into Brisbane and Melbourne need the widest contingency. New Zealand importers should confirm the actual port call before locking cargo-ready dates on services with alternating omissions.
### Global Container Market Snapshot
Global spot rates levelled out in late September. The Drewry World Container Index eased 1% to USD 4,468 per 40' on 24 September, with Drewry expecting further softening ahead of Golden Week. The SCFI ended a two-month run of weekly gains in week 39, and carriers are offering some October discounts on the major East–West trades. However, forward freight contracts are still pricing a rebound in November and December.
Rate movements on Oceania lanes have not followed the global indices closely. In early September, Shanghai–Australia spot rates were around USD 2,432/TEU and Shanghai–New Zealand around USD 2,634/TEU, excluding surcharges, before the September GRIs and the October restorations took effect.
**What this means for Oceania businesses**
A softer global index does not mean cheaper Oceania freight in October. Carrier restorations and peak demand on Asia–Oceania lanes are moving in the opposite direction to the main East–West trades.
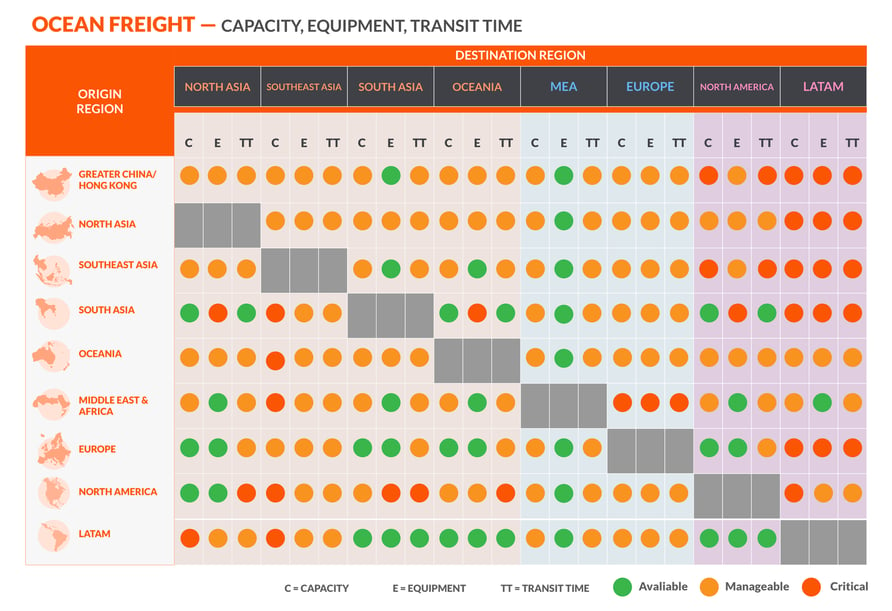
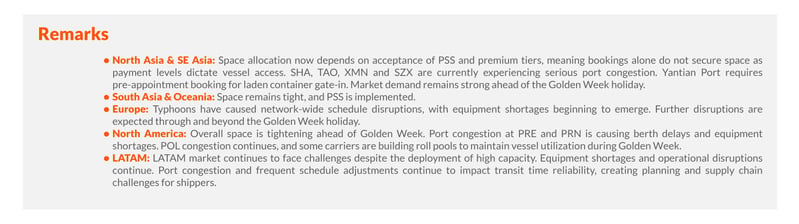
### Ocean Freight Snapshot (October 2026)
## Air Freight Updates
### **Air Freight: Demand Up 10% Year-on-Year, Ocean Overflow Adding Pressure**
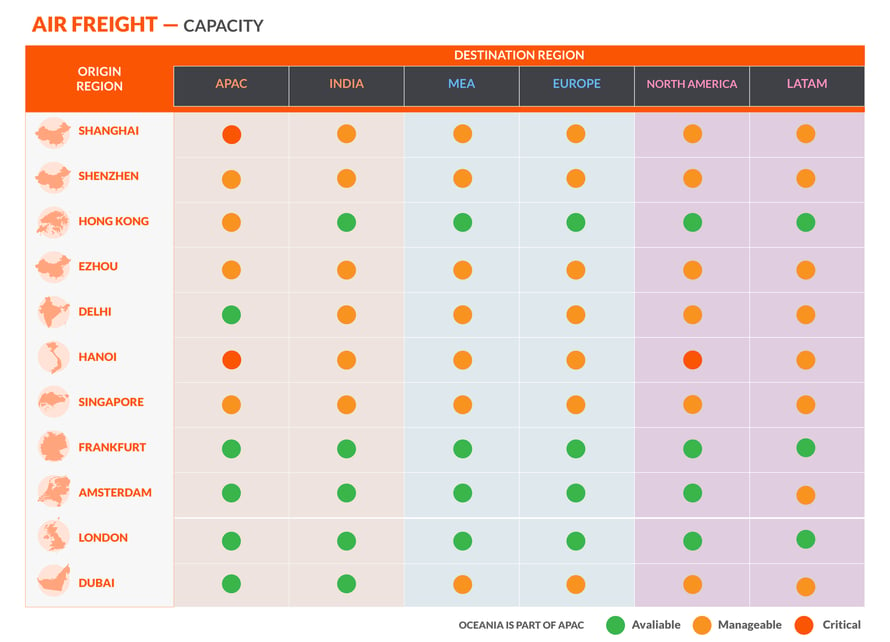
Air freight continued to absorb demand that ocean freight is failing to deliver reliably. Australia's air cargo market recorded imports approximately 10% higher year on year in July 2026, with that trend continuing into the September reporting period. Demand is tracking 7% above prior year across Australia and New Zealand air lanes, according to AXIMA and Navia Freight data. Capacity constraints are starting to ease slightly compared to the acute peak of the Gulf hub disruption, but pricing remains elevated relative to pre-conflict levels and airline supplementary charges continue to be reviewed.
China-to-Australia air freight rates for September were broadly flat to down slightly from August. The slight uptick reflects the early signs of pre-Golden Week mode-shifting as ocean congestion drives urgency. With September's two-round GRI adding another USD 1,000 per TEU to ocean costs, the cost differential between ocean and air has narrowed enough in some categories that the economics of air freight for high-value, low-volume cargo have become more compelling. Air freight demand is likely to rise further through October as Golden Week factory closures reduce ex-China ocean supply and importers with critical replenishment needs look to air for recovery.
Port Botany recorded a milestone in September: 504,000 TEUs moved by rail in FY2026, the highest rail freight throughput in the port's history. This is a positive development for Sydney import programmes, providing an alternative inland distribution pathway at a time when road transport congestion and costs are elevated following the August fuel excise restoration.
**What to do now**
- If you have Q4 Christmas-critical stock that has missed a September ocean sailing, model the all-in cost of air freight against the cost of a stocked-out or late-arriving October delivery. For high-margin, compact products, air recovery may be more cost-effective than waiting for the next available ocean sailing on a congested service.
- Golden Week will suppress available air capacity from Chinese origins during 1-7 October as passenger and cargo flights operate on reduced Chinese domestic demand. Book any air freight required for early to mid-October departure now, before the compression occurs.
- For air freight into Sydney, the Port Botany rail milestone suggests stronger than usual inland capacity availability. Confirm with your KLN Oceania team whether rail distribution is an option for your cargo's final destination.
### Rates Firm as Fuel Costs Climb
Air freight rates held firm through September. The Baltic Air Freight Index was up 20.9% year on year in the week to 21 September, with Hong Kong and Shanghai outbound rates both up close to 20%. WorldACD reported Asia Pacific spot rates rising for a third consecutive week to USD 4.69/kg in the week of 7–13 September. Gulf carrier capacity remains around 16% below mid-February levels.
Fuel is the main pressure point. Jet fuel prices were more than double year-on-year levels in mid-September, and carriers are lifting fuel surcharges. Xeneta has revised its full-year outlook to a 5–15% rise in air freight rates for 2026, noting that spot rates are plateauing but not falling. Forwarders do not expect a sharp peak this year, with demand supported mainly by high-tech goods rather than e-commerce.
**What this means for Oceania businesses**
Air remains a useful fallback where ocean schedules are unreliable, but budgets should reflect higher fuel surcharges through Q4. Converting to air early, rather than as a last-minute fix, will give better access to space and pricing.
### **Australia: Qantas Ground Handling Industrial Action**
Workers at Qantas ground-handling subsidiaries, including Australian airExpress, held protected industrial action across several Australian airports between 23 and 25 September, affecting freight handling in Sydney, Brisbane, Adelaide and Perth. Freight unloading and truck departures were disrupted, with Brisbane particularly affected. The dispute over pay and job security has not been resolved, and further action is possible.
**What this means for Oceania businesses**
Time-sensitive air imports and exports through Qantas Freight should include additional buffer until the dispute is settled. KLN Oceania will advise customers of any further action through customer advisories.
### **New Zealand: More Belly Capacity for Summer**
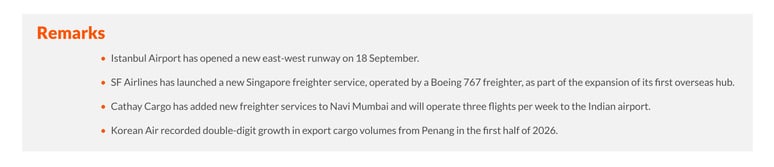
Christchurch Airport will offer a record 1.27 million international seats from November 2026 to March 2027, with 21% more flights than last summer. New Air New Zealand 787-9 routes to Singapore (late October), Tokyo Narita and Perth (both late November), along with additional Singapore Airlines and China Southern capacity, will add cargo space in passenger aircraft holds.
**What this means for Oceania businesses**
Additional belly capacity should help ease some of the air freight tightness New Zealand shippers experienced in September.
[](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)
### Air Freight Snapshot (October 2026)
## Customs, Inland Transport, Terminal and Regulation Updates
##### 
### **NZ: New Zealand–India FTA Enters into Force on 20 October**
The New Zealand–India Free Trade Agreement has been ratified by both countries and enters into force on 20 October 2026. From day one, 57% of New Zealand's exports to India will enter duty-free, rising to 82% at full implementation. Tariffs on sheep meat, wool and coal are removed immediately, and more than 95% of forestry and wood products become duty-free. Kiwifruit gains a duty-free quota around four times current average exports, while tariffs on mānuka honey and wine will be phased down over five and ten years respectively.
**What this means for Oceania businesses**
New Zealand exporters should confirm that products meet the agreement's rules of origin and that certificates of origin are in place for shipments from 20 October, to claim preferential tariffs from the start.
### **AU: Biosecurity Cost Recovery Changes from 1 November**
The second phase of the Department of Agriculture, Fisheries and Forestry's cost recovery changes takes effect on 1 November 2026. It introduces a revised fee structure, including fixed fees for most diagnostic activities on imported cargo. The first phase, which indexed most charges, took effect on 1 July. Final fee amounts should be confirmed against DAFF's published schedule.
**What this means for Oceania businesses**
Importers of goods that regularly require diagnostic testing should expect changes to how these costs are charged from November and may need to update cost models
### **AU/NZ: BMSB Season Reminder**
The 2026/27 [brown marmorated stink bug season](https://info.oceania.kln.com/knowledgehub/guide-to-2026/27-stink-bug-season-bmsb) runs from 1 September 2026 to 30 April 2027 for goods shipped from target risk countries. The shipped-on-board date on the bill of lading determines whether seasonal measures apply. Key changes this season include approval of ethyl formate for onshore treatment and removal of the rolled goods policy. Cargo arriving without compliant treatment documentation may be directed for re-export or destruction at the importer's cost.
**What this means for Oceania businesses**
With peak-season volumes arriving, confirm that suppliers and treatment providers are working to the 2026/27 requirements. Our customs brokerage team can help confirm current DAFF and MPI guidance.
### **AU: Anti-Dumping Measures on Steel Products**
The Anti-Dumping Commission has published findings on light steel studs and rails from China (Notice 2026/119, 15 September), with dumping duties of 33.3% for most exporters. A partial final ruling on galvanised steel from Korea and Vietnam followed on 18 September (Notice 2026/126).
**What this means for Oceania businesses**
Importers of steel building and construction products should check whether their suppliers and products fall within these measures before placing new orders
*Contact our KLN Oceania team for freight planning support, cargo insurance review, or customs brokerage advice specific to your programmes.*
[](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)
### Why Partner with KLN (Formerly Kerry Logistics Network)
Selecting KLN Oceania as your trusted partner isn't just a choice—it's a strategic move towards ensuring your success. Our commitment to excellence is not just a promise; it's a guarantee. With a global network that's both vast and meticulously managed, we stand head and shoulders above the competition. This means you benefit directly from unparalleled service quality, ensuring your supply chain needs are met with precision, efficiency, and minimal hassle.
Are you ready to elevate your logistics game and experience seamless support tailored to your unique needs? Let's discuss how we can bring unparalleled value to your business.
[](https://info.oceania.kln.com/hs/cta/wi/redirect?encryptedPayload=AVxigLLBg4uFRNwPdEn7g6JFaG2bMc73wTc1%2F%2BvDEYfd2CVoxas1j42jHYrEtLhFmeQpm6V54uE1aXvmSZy3P7TOvgjcc4HoqulFcNKfEp%2BwH7e11lkQbn6rSqEuWh5k835%2BMmKdAINU4vwn2Ofus8KIyAm2UDtYbYr9LqNBRvsFY5QLxWY1DykBvFpX7Dy7OdE%2ByQsTZJRsGII4V7iD&webInteractiveContentId=148519118772&portalId=40234550)

## Related articles
[View All](https://info.oceania.kln.com/konnect)
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - SEPTEMBER 2026](https://info.oceania.kln.com/konnect/konnect-september-2026)
04 Sep 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - AUGUST 2026](https://info.oceania.kln.com/konnect/konnect-august-2026)
31 Jul 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - JULY 2026](https://info.oceania.kln.com/konnect/konnect-july-2026)
08 Jul 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - JUNE 2026](https://info.oceania.kln.com/konnect/konnect-june-2026)
05 Jun 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - MAY 2026](https://info.oceania.kln.com/konnect/konnect-may-2026)
05 May 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - APRIL 2026](https://info.oceania.kln.com/konnect/konnect-april-2026)
30 Mar 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - MARCH 2026](https://info.oceania.kln.com/konnect/konnect-march-2026)
27 Feb 2026
[Konnect](https://info.oceania.kln.com/konnect/tag/konnect) [KONNECT - DECEMBER 2025](https://info.oceania.kln.com/konnect/konnect-december-2025)
05 Dec 2025
### Notices
### Company
### Locations
Connect with KLN Oceania
[](https://www.linkedin.com/company/29366171/)
[](https://www.kln.com/)
© 2026 KLN FREIGHT (OCEANIA) LIMITED. ALL RIGHTS RESERVED.
- [Trading terms](https://oceania.kln.com/legal/trading-terms/)
- [Terms & conditions of use](https://oceania.kln.com/legal/terms-conditions-of-use/)
- [Privacy policy](https://oceania.kln.com/legal/privacy-policy/)
- [Disclaimer](https://oceania.kln.com/legal/disclaimer/)
```json
{
"@context" : "https://schema.org",
"@type" : "BlogPosting",
"author" : {
"@type" : "Person",
"name" : "KLN Oceania",
"url" : "https://info.oceania.kln.com/konnect/author/kln-oceania"
},
"dateModified" : "2026-10-02T04:42:03.786Z",
"datePublished" : "2026-10-02T04:41:36.000Z",
"headline" : "KONNECT - OCTOBER 2026",
"image" : [ "https://info.oceania.kln.com/hubfs/banner%20konnect%202026%202.png" ],
"mainEntityOfPage" : {
"@id" : "https://info.oceania.kln.com/konnect/konnect-october-2026",
"@type" : "WebPage"
},
"publisher" : {
"@type" : "Organization",
"logo" : {
"@type" : "ImageObject",
"url" : "https://info.oceania.kln.com/hubfs/KLN%20Logo_colour.jpg"
},
"name" : "KLN FREIGHT (OCEANIA) PTY. LTD."
}
}
```